Every so often, a headline claims most people should take Social Security as early as possible. It makes for great clickbait, but not great advice.
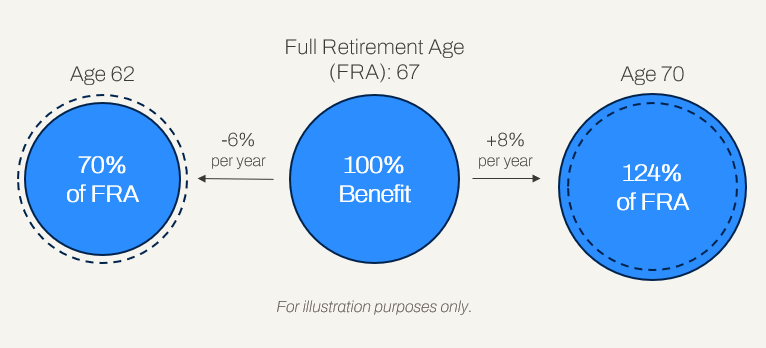
Let’s set aside that the financial media too often offers a one-size-fits-all solution on decisions that are incredibly personal. The fact is, for most retirees, delaying benefits remains one of the most reliable ways to increase lifetime income. Waiting until age 70 can boost your monthly benefit to 124% of your full retirement age benefit—a 77% increase from the reduced benefit offered at age 62. That’s inflation-protected growth and hard to replicate anywhere else with so little risk.
Also often overlooked in the headlines: the decision to delay (or not) isn’t just about you—it’s about protecting your spouse. When one spouse passes away, the survivor keeps the higher of the two benefits. Delaying the higher-earning spouse’s benefit until age 70 can significantly increase the lifetime income received by the surviving spouse.
All of that said, even our general rules don’t apply to everyone. Not every client is married. Other clients hold most of their wealth inside a pre-tax retirement account; in their case, claiming their Social Security benefit early—and thus, delaying portfolio withdrawals—reduces taxes and increases after-tax wealth.
Expect Social Security to be back in the headlines this summer when the annual report on the program’s health is released. Just remember: the right strategy for you depends on your goals, health, taxes, assets, and family situation.
That’s why we’ll run the analysis with you, to offer truly personalized advice that beats any headline.