Portal
Let's talk
  • What we do
    • Wealth management services
    • Our approach
    • Working together
  • About us
    • Our team
    • Our company
    • Community engagement
    • News and events
  • Insights
  • Careers
  • Contact us
  • Portal login
  • Disclosures
The latest insights
  • The midterms and your portfolio: what history tells us
  • Separately Managed Accounts: What they are and when they make sense
  • All-time high? Or just another Thursday?

A Better Portfolio? Simple, But Not Easy

April 11, 2017
Author: Dougal Williams, CFA

Nearly 25 years have passed since the research of Professors Eugene Fama and Ken French helped answer one of the most important investment questions ever to face investors: “What explains the differences in stock returns?”

Prior to Fama and French’s 1992 paper, The Cross-Section of Expected Stock Returns, it was long believed returns were best explained by a stock’s sensitivity to the market, known as beta. Bill Sharpe won a Nobel Prize in 1990 in part for his capital asset pricing model (CAPM), which linked a stock’s expected return with its beta. Stocks with betas above 1.0 were thought to offer returns higher than the market, while betas under 1.0 implied below-market results.

Fama and French, however, highlighted several violations of the singular link between market beta and returns. Studying stock returns from 1963-1990, the researchers found small cap and low-priced stocks had significantly higher returns, in both U.S. and international markets, than predicted by their market betas alone. By adding size and value to Sharpe’s

CAPM, Fama and French could explain nearly all the performance difference of stocks and portfolios over time.
Importantly for investors, Fama and French’s conclusions provided a framework to construct better portfolios. Want higher expected returns? Simple—increase your portfolio’s exposure to small cap and value stocks.

But would their theory of expected returns translate into realized returns? We now have nearly twenty-five years of data to help answer that question:
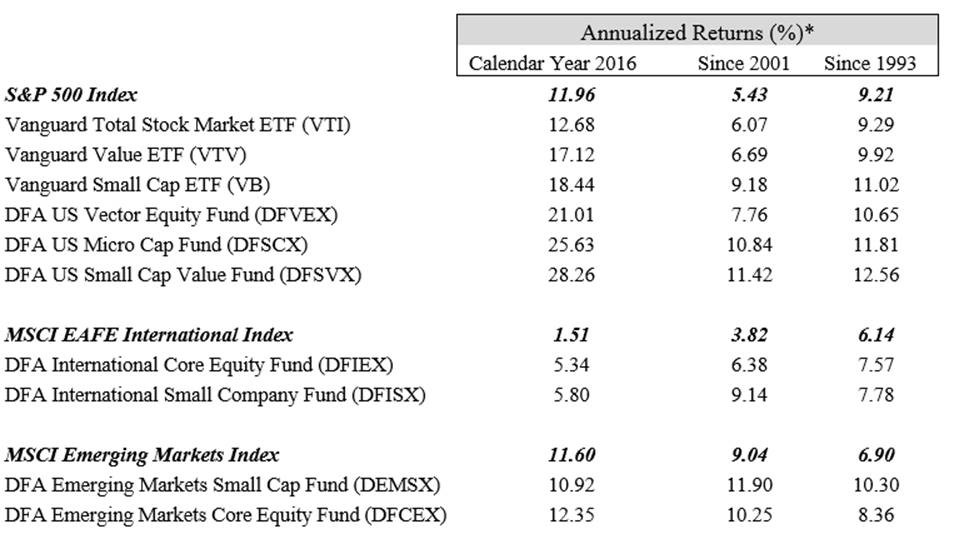
The table above shows annualized returns for the small cap and value strategies we favor in client portfolios. The data is presented to reflect how these funds performed in calendar year 2016—a great year for small cap and value stocks around the world—as well as during two longer time periods: since 2001, the year Vista opened its doors, and since 1993, the year after Fama and French published their research.

These results confirm what Fama and French proposed back in 1992—investors were likely, but not guaranteed, to earn higher returns by favoring small cap and value stocks. While returns for the entire period have been impressive, it must be acknowledged that owning a portfolio which does not move in lock step with “the market” can at times be discouraging.

Consider the six years ending in 2000: small cap stocks underperformed the popular S&P 500 by 12% per year! And from 2007-2015, growth stocks in the U.S. outpaced low-priced value stocks by an average of 4% per year. Such long stretches of underperformance can test the resolve of even the steeliest of investors.

They also serve as a great reminder that building a better portfolio may be simple in theory, but capturing those higher expected returns sure isn’t easy.
Dougal Williams, CFA

Connect with Dougal


Article tags
Economy and marketsInvestment research

Related articles
Investing

The midterms and your portfolio: what history tells us

November 5, 2026By Alex Canellopoulos, CFA, CFP®

Stocks have advanced under Republican, Democratic, and mixed control of Congress. The evidence favors staying invested and diversified over reacting to elections.

Investing

Separately Managed Accounts: What they are and when they make sense

October 19, 2026By Alex Canellopoulos, CFA, CFP®

Separately managed accounts offer direct ownership of individual securities, which can create added tax-management opportunities for investors whose circumstances warrant it.

Investing

All-time high? Or just another Thursday?

September 11, 2026By Joe Rayburn, CFP®

New market highs can feel unsettling, as if stocks can’t climb any higher. But history shows something different. We look at the data, and why staying the course is key.

Subscribe to agenda-free news, tips, and analysis, delivered to your inbox.

This field is for validation purposes and should be left unchanged.
  • Legal Disclosures
  • Form CRS
  • Client Portal
  • Cookie Policy
  • Legal Disclosures
  • Form CRS
  • Client Portal
  • Cookie Policy
  • Legal Disclosures
  • Form CRS
  • Client Portal
  • Cookie Policy
Contact us
© Vista Capital Partners 2026. 100% employee-owned.
Manage Consent

We use cookies to track website performance. View our Privacy Policy for details.

Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}